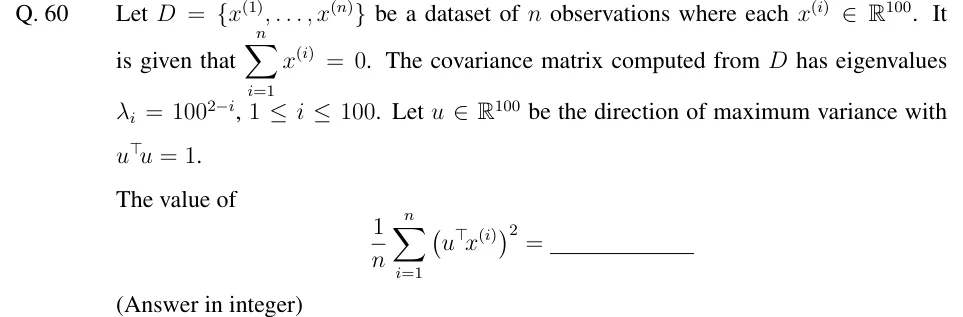
Let be a dataset of observations where each . It is given that . The covariance matrix computed from has eigenvalues , . Let be the direction of maximum variance with .
The value of ______
(Answer in integer)

Let be a dataset of observations where each . It is given that . The covariance matrix computed from has eigenvalues , . Let be the direction of maximum variance with .
The value of ______
(Answer in integer)
ANSWER
The value is , the largest eigenvalue of the covariance matrix.
Official answer: 100Source: Official answer key, GATE 2025 DA (IIT Roorkee)
The data are centred, , so the sample mean is . The covariance matrix (with the convention, which is the one the quantity in the question matches) is
Expand the required quantity:
Because the mean is zero, is exactly the variance of the data projected on the unit vector .
is symmetric, so write with orthonormal eigenvectors . For a unit vector with , we get . Equality holds when is the eigenvector of the largest eigenvalue. So the direction of maximum variance gives .
The eigenvalues are , which strictly decrease as increases: , , , and so on. Hence .
Therefore
KEY IDEA
For centred data, the mean squared projection on a unit vector equals , the variance along . The direction of maximum variance (the first principal component) gives the largest eigenvalue of .
WATCH OUT FOR
Reading with the wrong index and taking or instead of . Another slip is to report the sum of all the eigenvalues, which is the total variance, not the variance along the single top direction.
From the GATE 2025 DA paper. Every question of this paper · Download the full paper · All 2 PCA questions, with notes